Investor Insights Blog|Ryan Wright Interview Part I: Getting Started in Real Estate, Mistakes to Avoid, Rules to Follow & More
Real Estate
Ryan Wright Interview Part I: Getting Started in Real Estate, Mistakes to Avoid, Rules to Follow & More
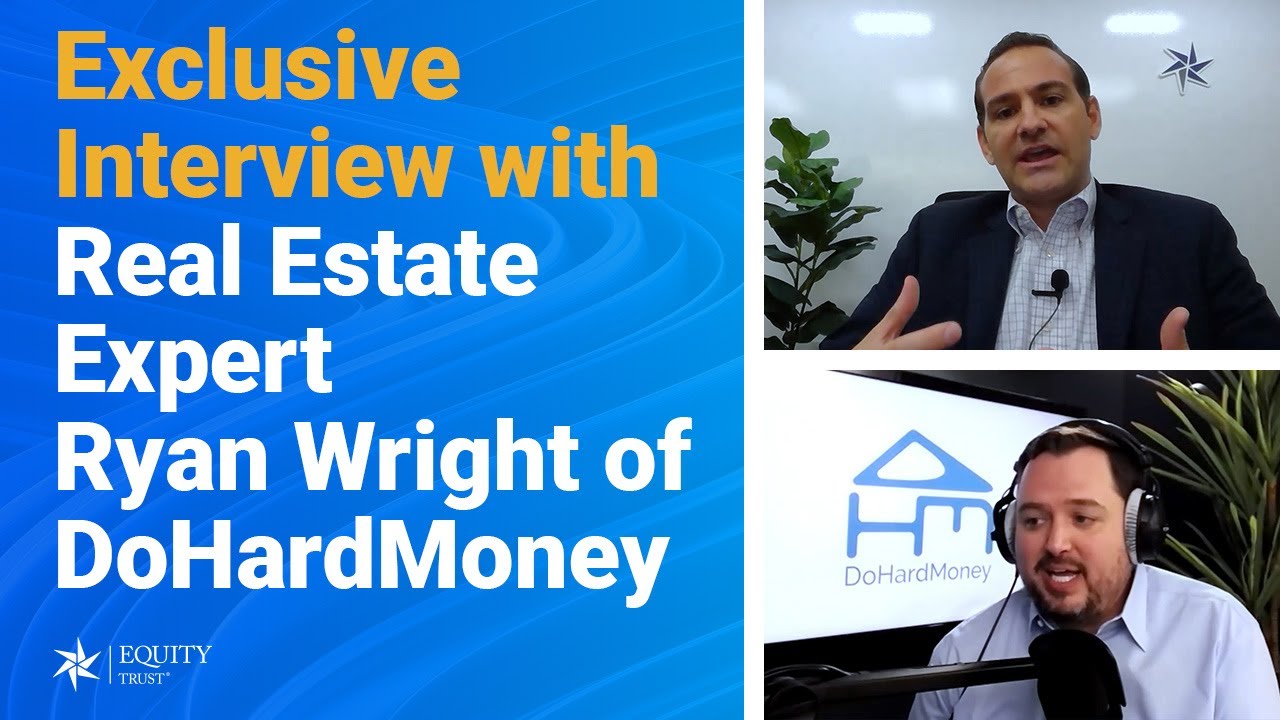
In part one of this exclusive interview, Equity Trust Educational Speaker, John Bowens, sat down with Ryan Wright of Do Hard Money to discuss how he got started in real estate, what mistakes he learned as an investor, how he grew to own his own business and what Do Hard Money is all about.
John: Really excited to have Ryan meet with me today. Ryan is an Equity Trust client. He is a real estate investor, licensed agent, he has been real estate for nearly two decades, I believe, if not more, he has run businesses. He runs his own real estate business now. His company is Do Hard Money.
And so I thought what better than Ryan right to be on today’s call with us to educate other Equity Trust investors or individuals that are interested about what does it take to get involved in real estate? How does it work, and how to do it with a self-directed IRA. So, Ryan is a real estate practitioner as well as a self-directed. Thank you so much for joining us.
Ryan: I’m happy to be here. Thanks for having me.
John: Absolutely. We’re going to jump right into it. Ryan, for our audience, if you could start off with talking a little bit about, you know, what’s your philosophy in real estate?
How did you get involved in real estate? What was the purpose for you in really getting you to where you’re at today and what your business looks like today?
Ryan: I always tell people, I don’t think I really had a choice.
My grandpa was an HVAC contractor. On the side, he’d buy properties, fix them up and sell them before HGTV and all those things were popular. My dad was a chiropractor. And he just knew the way to wealth, even though he had his day job. And I think this is a really important point because a lot of us have that situation. He’s had his day job, but he bought duplexes, triplexes, etc.
He’d buy one, he’d fix it up and sell it. I spent the summers working with my grandpa fixing up a three-plex into a six-plex and painting and carpeting. There’s a lot of sacrifice that happens early on to make that a reality. But with time, you know, when I saw that happen over a decade, I saw those property values go up, I saw money be manmade. So I knew there was money in real estate.
And that’s kind of where it all started for me. I got my real estate license, and then I started helping people then I started doing. I kept buying plexes and rentals and I sell or I helped other people fix and flip. Then I started fixing flipping then I started lending. Now we provide tools and services to help other people wanting to get into the real estate investing game and capital as well. So that’s kind of the quick, the quick version.
John: Awesome, thanks, Ryan. And we were talking before this and sharing some of our, I guess you call it, you know sort of war stories and talking about on the shop floor, what happens when you’re running a real estate business as either a part-time investor or full-time investor. I understand that there are folks out there that are part of our group that are full-time investors. And they’re also people that are part-time investors.
I consider myself a part-time investor. I spend most of my time representing Equity Trust Company and teaching and educating other investors on how to utilize a self-directed IRA. And then I do my own investing with my self-directed retirement accounts on my own time.
We were sharing our first deal stories. I know for me, I was absolutely filled with fear. And all I had at that time was $23,000 in my retirement account. I wanted to invest in real estate and I made a private loan to a real estate rehabber. I was very fortunate to get my money back in less than six months, and it was all tax-free. It was that first deal that then catapulted me into the second and third and the fourth, and so on and so forth.
Could you share what that first deal looked like for you?
Ryan: Yeah, I mean, the first deal for me was ugly. You know, so I was 21 years old, I had seen my dad buy plexes. And so I bought a duplex, I probably paid full retail for it even though it needed work. I was just so anxious to get into the game. And the plan that I had was to turn the duplex into a three-plex.
I didn’t realize you had to talk to the city and get their permission and we had parking issues. So I turned it into a three-plex. And then the city came out and said we had violations and then I had to turn it back into a duplex. Then I turned it into a mother in law. And then I ended up moving into the property. The idea was to buy it, rent one side or two of them, and then live on the other.
In the end, one of the blessings of real estate is if you can, if you can hold on to it, you’re usually going to make some money, and so years later, even though I bought it full retail and made probably every mistake you could have in the book, I ended up making money and it catapulted me into buying the first house that we actually bought to live in ourselves that wasn’t an investment property.
But yeah, it was is. It’s one of those things where you can talk about the temperature of the water, you can put the thermometer in there. But until you actually jump in, you don’t actually feel what it feels like.
John: Yeah, and I’m the opposite. I started in private lending, and now I own rental property.
Ryan: And private lending could certainly be a great entry point. But you got to do your due diligence on deals like that as well.
John: Right. And, you know, I could certainly tell horror stories of deals that went south or of deals that unfortunately didn’t pay off to the expectations that I had.
Ryan, you also have experience with private lending, which it sounds like came after you actually got involved in owning physical real estate?
Could you speak a little bit to your private lending experience, and maybe even what you do today. Some people might refer to it as hard money lending, but I like to refer to it as private lending.
Ryan: Yeah, no, I’m with you. Yeah, I am an investor first. That’s kind of where I came from. So a lot of people come from the banking world and get into money, lending money, I came from being an agent to being an investor. And one of the things I found there was just such a need for hard money, private money in the marketplace, there was just such a need.
When I was doing my first deal, my first fix and flip, I didn’t know how to get the funding for it. I had some money, I didn’t have a lot of money, I had good credit, but I didn’t have amazing credit. And I needed somebody to do a deal for me.
I found a guy named Dan and he funded the purchase the rehab didn’t have me make any payments until I sold the house. And that guy literally changed my life. So as I’ve done my own fix and flips that I’ve done wholesaling, as I’ve done rentals, I’ve always wanted to be able to help other people as well. And lending was a natural fit for that.
One of the things that we do now is will we lend money. We’ll end the purchase, we’ll end the rehab, lots of times, we’ve been the closing costs if you buy a good enough deal to people. And what we do is we take private investors that have capital and we have people that need money, we vet the deals and find those and matchmake, the two of those together, so that people with money can have good opportunities, and people that need money can get access to that.
When put a platform together with those, we can take care of those transactions for people. So that’s kind of the big stuff that we’re doing right now.
John: That’s great. And, Ryan, I’m glad you brought that up, because one of the questions that a lot of investors will have about Equity Trust and self-directing a retirement plan. And how does that work from a financial institution perspective.
We don’t provide tax legal or financial advice. And we don’t do due diligence on the investments that individuals make, it’s up to the client to direct the funds, they give the direction to Equity Trust, and we process the transactions. We provide a lot of education and training and information, but where we don’t cross the line is providing advice for doing a background check on a borrower or due diligence on a specific investment to determine suitability for that individual’s portfolio.
And that’s really the beauty of a self-directed IRA is the ability to be able to take control and make all of those financial decisions. And you’re obviously a great representation of doing that, performing the due diligence. I know some failures along the way that you’ve learned from in order to you know, do better do a better job of performing that due diligence, as it pertains specifically to private lending.
Could you share a little bit about maybe one of the experiences that you’ve had that maybe wasn’t as favorable? And what the lessons were that you learn from it from a due diligence perspective?
The big mistake people make is they overvalued the property and they underestimate the repairs. In addition, they don’t do a great job on the project management getting the project done on time and on budget.
Ryan Wright, DoHardMoney
Ryan: Yeah, absolutely.
There was a property in Virginia I was actually the private money lender. We gave a loan on the property. And one of the things that we found out pretty early, the borrower ended up not doing the work like they said they were going to do.
Keep in mind, it’s all about risk reward. It’s this risk reward, how much I can charge versus what they’re doing. But on this specific property, the borrower didn’t finish the rehab. So and I think where we could have done a lot better and we’ve now changed this is ensuring that work got done by doing forced inspections, getting people out there, making sure that work was getting done on time.
The second big problem that we had is we’ve had work get done, but the quality, the workmanship just wasn’t there. We had an inspector go sign off on something saying this was good. But it ended up that it wasn’t good. And it had to be torn out and redone all over again, which is really expensive to pay for it twice. So we ran into some situations like that.
Another problem was this little house was in a pocket of just really bad area, everything around, it was pretty good. But there’s just this little pocket, that was just a bad neighborhood. And we looked at this and looked at values, but it really seemed like there was enough values in the area. I couldn’t go more than just a few blocks to get values because the ones in this specific neighborhood were selling drastically less than the ones just a few blocks, you know, five blocks away a mile within the mile radius.
We’ve learned so much since then. But the idea is, number one, don’t overlook comparables.
I find that’s a big thing that private investors make mistakes on is they really look for the most expensive house that’s ever sold and say this is what it’s going to sell for. And we flipped that and said, let’s think like a buyer thinks. A buyer is going to say what’s the least expensive homes that are out there.
The other thing is how we manage in our contractors and what we require and put them through and make sure they’re licensed and how we do inspections. I think we lost $30,000 on that loan that we actually gave. And it’s really easy to cry about that I hate losing money on any individual loan. But keep in mind, I have to look at the overall portfolio and how many loans I have out there and what my rate of return was on all of the loans that I was actually doing
I can do a few loans to make up that loss pretty easily. But I can also not have to go through those problems and get some help with due diligence. And that’s not going to solve everything, you’re still going to get some bruises. But it should eliminate a lot of the big problems that you’re running into if you’ve got some due diligence that’s being done appropriately.
John: Right, got it. What would be the best first step for someone to get started in that particular space?
Ryan: Yeah, I think it depends on your experience level, like if you have some background.
If you’re saying they don’t have experience in real estate, let’s say it’s a doctor or lawyer or CPA or whatever the case is, that’s got money, high income, one thing they can consider is finding somebody to help them like a mortgage broker or somebody that has experienced doing due diligence, something like we do, so that they can help them say, here’s the rules we recommend you play by. And we’ll only bring you deals that fit these rules.
One of the biggest problems you have, if you don’t have the real estate experience is finding deals. Finding deals is hard, we get over, I don’t know, 200 loan applications, we end up closing on a dozen of those in a month.
Those are like the three Cardinal sins:
Don’t overvalue the property.
Don’t underestimate the rehab
Make sure the work gets done on time and on budget
And anything you can do to make sure those three things are happening is going to be put you ahead of the game.
The other thing that you really run into is it’s a risk and reward. Some people may say, Oh, I saw this guy charging five points. And, you know, I’ve seen this guy charge in two points and 12percent or 15percent. net. So it’s all relative because the reality is you take on more risk.
If you’re working with a borrower that’s never done it, you take on some more risk. If you’re working with a borrower that has not a lot of money into it, you take on some more risk.
If you take on a borrower that doesn’t have the best of credit, you take on a little bit more risk. You know, if you take on a borrower that has maybe had some experience in the industry, and has done a fix and flip, you take on a little less risk. It’s this whole risk-reward ratio.
And one of the things I’d say for people just getting started is to know where your tolerance is, and maybe you need to bucket out your money and say, “Hey, I’m going to do lending, I’ve got a half a million bucks or a million dollars, whatever the case is, I’m willing to put 20percent into higher risk loans 20percent into, you know, your easy loans and 20percent or 25percent,” whatever the ratios you want to do there and bucket that out for yourself.
It’s going to be really tempting to do some of these loans that are really sexy on paper where they make a lot of money, but there’s a higher risk that comes with that.
Whereas if we’re dealing with loans that are or maybe a safer loan that are produced a lower return so realize there is a risk-reward. Not every borrower is created equal. Not every property’s credit is equal. You’ve got to look at it as a holistic approach.
1
How do I sell a property owned by my IRA?
When you’re ready to sell a property that’s owned by your IRA, you need to request the original documents from Equity Trust. This is done by completing an investment form, which can be found on myEQUITY. Once the property has been sold, all funds from the sale must be deposited into your IRA. These funds must be sent to Equity Trust with a payment coupon.
2
What investment options are possible with an Equity Trust account?
Some of the investments Equity Trust clients make using their self-directed accounts include real estate, tax liens, digital currencies such as Bitcoin, private lending, purchasing notes, private placements, precious metals, forex and other investment options that are permissible under IRS guidelines.
3
What is a self-directed IRA?
A self-directed IRA is a retirement account that allows for investments in alternative assets such as real estate, promissory notes, and precious metals, in addition to stocks and mutual funds. The account owner determines how they would like to manage their account and directs the custodian to process the transactions within the account. In addition to Traditional and Roth IRAs, other accounts such as SEPs, SIMPLEs, Solo 401(k)s, health savings accounts, and Coverdell education savings accounts can be self-directed as well.
Join over 100,000 subscribers who receive investing and wealth-building news and education in their inbox.
You are leaving trustetc.com to enter the ETC Brokerage Services (Member FINRA/SIPC) website (etcbrokerage.com), the registered broker-dealer affiliate of Equity Trust Company. ETC Brokerage Services provides access to brokerage and investment products which ARE NOT FDIC insured. ETC Brokerage does not provide investment advice or recommendations as to any investment. All investments are selected and made solely by self-directed account owners.
We use cookies to improve your experience on our site. By using our site, you consent to cookies.
Cookie Preferences
When you visit our website, we and our vendors use cookies and other online tracking technologies ("Cookies") to enhance user experience, analyze website performance and traffic, and provide marketing and advertising.
We use certain Cookies to enable the website to function, including for website security and to remember your settings and privacy preferences. These Cookies are always active. You can set your browser to block or alert you about these Cookies, but if you block these Cookies, some parts of the website may not function properly.
A sale of personal information can refer to disclosures of personal information to third parties who may use the information for their own purposes, such as Cookie vendors. Similarly, sharing personal information refers to disclosing personal information to third parties for cross-context behavioral advertising. In this context we sell and share personal information through our website. If you would like to opt out of sales and sharing for cross-context behavioral, please opt out of the Targeting and Analytics sections below. If you choose to use the Global Privacy Control (GPC) browser signal, you will be opted out of sales and sharing for cross-context behavioral advertising associated with the browser for which you have enabled the signal. If you use multiple browsers or devices, you will need to activate the signal for each one that you use.
You can manage your Cookies at any time by clicking the "Do Not Sell or Share My Personal Information" link in the footer of the website.
Please see our Privacy Policy for more information about our privacy practices.
These Cookies are necessary for the website to function and are always active. These Cookies are used, for example, for the security of our website and to administer your privacy preferences. You may configure your browser to block or alert you about these Cookies, but some parts of the website may not function properly if you do so.
Name
Description
Duration
Geolocation Config
This cookie is used to store the consent settings based on the visitor's location.
365 days
Cookie Preferences
This cookie is used to store the user's cookie consent preferences.
365 days
CloudFlare provides web performance and security solutions, enhancing site speed and protecting against threats.
The _cfuvid cookie is only set when a site uses this option in a Rate Limiting Rule, and is only used to allow the Cloudflare WAF to distinguish individual users who share the same IP address.
session
cf_clearance
Whether a CAPTCHA or Javascript challenge has been solved.
session
__cfseq
Sequence rules uses cookies to track the order of requests a user has made and the time between requests and makes them available via Cloudflare Rules. This allows you to write rules that match valid or invalid sequences. The specific cookies used to validate sequences are called sequence cookies.
session
cf_ob_info
The cf_ob_info cookie provides information on: The HTTP Status Code returned by the origin web server. The Ray ID of the original failed request. The data center serving the traffic
session
cf_use_ob
The cf_use_ob cookie informs Cloudflare to fetch the requested resource from the Always Online cache on the designated port. Applicable values are: 0, 80, and 443. The cf_ob_info and cf_use_ob cookies are persistent cookies that expire after 30 seconds.
session
__cfwaitingroom
The __cfwaitingroom cookie is only used to track visitors that access a waiting room enabled host and path combination for a zone. Visitors using a browser that does not accept cookies cannot visit the host and path combination while the waiting room is active.
session
cf_chl_rc_i
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
cf_chl_rc_ni
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
cf_chl_rc_m
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
__cfruid
Used by the content network, Cloudflare, to identify trusted web traffic.
session
__cf_bm
Cloudflare's bot products identify and mitigate automated traffic to protect your site from bad bots. Cloudflare places the __cf_bm cookie on End User devices that access Customer sites that are protected by Bot Management or Bot Fight Mode. The __cf_bm cookie is necessary for the proper functioning of these bot solutions.
session
__cflb
When enabling session affinity with Cloudflare Load Balancer, Cloudflare sets a __cflb cookie with a unique value on the first response to the requesting client. Cloudflare routes future requests to the same origin, optimizing network resource usage. In the event of a failover, Cloudflare sets a new __cflb cookie to direct future requests to the failover pool.
session
Google Tag Manager loads the site's other analytics and advertising tags. It sets no cookies of its own; each tag it loads is listed under its own category and only runs with the consent that category requires.
Set on m.stripe.com to help Stripe detect fraudulent payments.
2 years
These Cookies help us understand how visitors interact with our website by collecting information about usage, traffic, and website performance. This information helps us improve the website and user experience.
Crazy Egg records how visitors scroll, click and move through pages (heatmaps and session recordings). Form fields are masked before any data leaves the browser.
Set by Cloudflare on Unbounce's content domain (js.ubembed.com) to distinguish people from automated traffic.
30 minutes
These Cookies are used by us and our advertising and marketing partners to deliver more relevant content and advertisements. They may collect information about your browser, device, and interactions across websites to help tailor advertising and measure campaign effectiveness.
Google Ads measures the results of advertising and builds audiences for showing relevant ads.
One cookie per offer (the name ends in the offer ID), recording that the visitor has already seen it.
30 days
_omappvs
Records the current visit, to decide which offers to show.
20 minutes
_omappvp
Records that the visitor has been to the site before, to decide which offers to show.
13 months
These Cookies enable enhanced features and personalisation, such as remembering your preferences and providing additional functionality. They may be set by us or our vendors. If disabled, certain website features may not operate as intended.
Calendly provides appointment scheduling for booking a consultation. The cookies below are set by Calendly's content delivery network.