When a Performing Note Stops Performing: Your Options
The following was written by guest blogger Aaron Halderman, owner of NoteWorthyUSA.com.
If you hold performing notes or are considering them as an investment option, it’s helpful to be prepared for potential scenarios.
For example, what happens when a performing note stops performing? I’d like to explore some of the solutions available to an investor.
The first step in this process – in fact, it should occur even before a note is purchased – is to assess the risk. Just like when you’re buying a stock, the best time to research is before you buy.
We spend a lot of time in our webinars and podcast teaching investors how to determine the value of a note. Much like appraising a property, this is not an exact science. However, I’ve outlined six components you should always take into consideration.
Due diligence should be performed on each of the following items:
The payor’s financial information (credit score, income statement, etc.)
The value and type of collateral (single-family home, mobile home, etc.)
The amount of the down payment
The terms of the note (interest rate, payback period, etc.)
The amount of seasoning (length of payment history)
The paperwork (recorded properly, etc.)
Now before you shut down and think: “Yikes! That looks like a lot of work,” keep in mind that much of this information is fully documented and a part of public record. In addition, third-party providers service many of these notes, and these servicing companies can provide well-documented transactions.
Performing due diligence in each of these six areas will enable you to weigh the redeeming and non-redeeming factors of any note. In addition, you will gain invaluable insight into how well the note will perform. And finally, these factors will be used to set your maximum investment-to-value ratio.
Scenario: a late payment
Let’s assume you completed your due diligence, and everything is going well. You purchase your note, maybe you modified it to facilitate payment, and then all of a sudden… a payment is late.
If this happens, it is very important to set the precedent that you take this very seriously. If you do not do that right from the start, the payor will sense your reluctance and you will likely be setting yourself up for future problems. Unfortunately, it is very easy for new landlords to become sympathetic and let the tenant get away with not paying late fees. More often than not, once that happens, the tenant will start being late every month.
This is one of the reasons we always recommend that clients have their notes serviced by a professional servicing company. These companies know the paperwork. They know what and when to file and document everything. And, perhaps most importantly, their services are typically not expensive at all.
Bottom line: If a payment is late, what should you do? Let your servicing company handle it! If it looks like a temporary glitch, a loan restoration fee can be paid, and things will remain the same. If it’s more of a long-term issue, the loan could be modified to lower the tenant’s monthly payment. These are simple problems.
Scenario: Inability to pay
Now let’s assume there is a big problem. The tenant lost his/her job and is unable to pay. Your performing note is now a non-performing note. At this point, you must tell your servicing company how you would like them to proceed. There are three primary legal options available: short sale, deed in lieu, or foreclosure. Let’s examine each one individually.
Shorten your headaches with a short sale
Very simply, a short sale occurs when the lender (note owner) agrees to accept less than what is owed in principle balance to facilitate a sale of the property. Literally, the note owner is willing to “short” what he/she is owed. Since you are the note owner, it is very simple for you to coordinate this step with the payor and your servicing company.
For example, let’s say you paid $70,000 for a performing note with a $100,000 remaining balance (principal balance). The property backing this note is worth $110,000. Perhaps you have received payments for 12 months and now the payments have stopped because the payor lost his/her job.
The property may sell for $110,000; however, it may also sit on the market for a while. Since the payor owes you slightly less than $100,000 (the 12 payments that were made consisted predominantly of interest), you could offer to forgive the debt and authorize the property to be sold for $90,000. At this price (a discount of 18.2 percent to the market value), it should sell very quickly. After the sale, the payor is then relieved of the debt. Most importantly, you receive a check for $90,000 from the sale.
Bottom line: You invested $70,000. In return, you received 12 months of payments – or $10,800 based on monthly payments of $900 – and a lump sum of $90,000. That’s a total return of $30,800 on a transaction that may have taken just 15 months from start to finish.
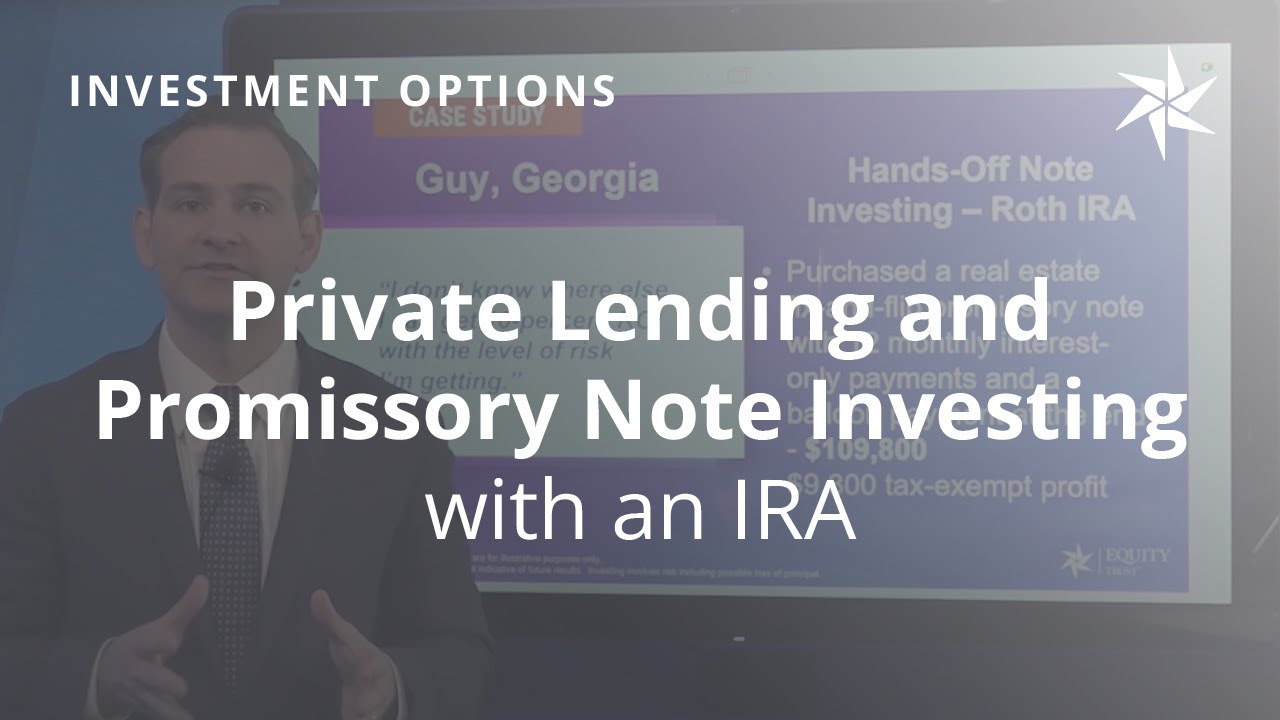
Video: Private Lending and Promissory Note Investing with a Retirement Account
This DIL (deed in lieu) isn’t dill
A deed in lieu (DIL) is a voluntary surrender of the deed (title to the property). In this option, the payor simply signs the document and vacates the property in exchange for debt forgiveness. In most cases, this is a much better alternative to foreclosure for the payor as well as the note owner.
The only time when this is not a good move for the note owner is when there are other junior liens on the property. However, if you conducted your proper due diligence, you should already be aware of any other liens.
If you take a DIL, you assume the junior liens as well. Sometimes those liens can be negotiated down or even removed from the property. Again, this is where a servicing company and other professionals can help.
Bottom line: A DIL is a quick and inexpensive solution. The payor gets to walk, and you get the property and all the rights.
Foreclosure: The final frontier
Going back to our example, let’s assume the numbers just didn’t work for a short sale. Furthermore, the payor is totally unwilling to do a DIL. In this situation, you simply enforce the mortgage and take it to foreclosure.
The drawback is this may take time and some additional costs. However, if you have invested properly (i.e., our due diligence was comprehensive and accurate), you will end up with a property whose value far exceeds the price you paid for the note.
The foreclosure process varies from state to state, so it is extremely important that you familiarize yourself with these differences before you buy a note. Regardless of the state-to- state nuances, there are essentially two things that can happen at the foreclosure sale. And the good news is that both results are positives for the note owner.
As the note owner, you get to set the minimum bid price. If no other bidder trumps that price, you get the deed. Not only that… all junior liens are wiped away.
On the other hand, if there are higher bids, you cash out at the foreclosure sale.
So, let’s assume the note owner (you) has decided to take this mortgage to foreclosure. You could set the minimum bid for what you are still owed. Using the same numbers as before, this would be just a tick below $100,000. Let’s say $99,000. At this price, the odds are not good that another investor will step up and bid higher, considering the property value is $110,000.
If there are no other bidders, you get the deed for money owed and all liens are wiped away. So, you get a property valued at $110,000 for a total investment of $70,000 (your initial investment) minus whatever the tenant has paid up to that point.
If, on the other hand, there is another bidder – say someone steps in at $99,500 – then you will get paid up to the minimum bid or $99,000 in this example. Either way, you are profiting.
Now let’s assume you really just want to cash out rather than get the deed. If that’s the case, simply lower the minimum bid to a more palatable amount. For example, you could set a minimum bid of $85,000. At this level, there’s a strong chance that another bidder will come in with a higher offer and purchase the property. Assume the bid comes in at $85,500; you walk away with $15,500 plus whatever the tenant had paid you up to that point.
Bottom Line: Foreclosure is your ultimate fallback solution. You either take ownership of the property free of liens, or you get cashed out at the auction. And you don’t even have to attend the sale. A representative from your servicing company can do that for you.
Once you have the deed, either through DIL or foreclosure, you have numerous exit strategies. Here are just a few:
Sell it as is to a cash buyer
Fix and resell the property at retail price
Seller finance to new owner
Seller finance to investor as loaded rental
About Aaron Halderman
Aaron Halderman has over 15 years of real estate development, distressed debt management, and financial services experience. Aaron owns NoteWorthyUSA.com and is the publisher of the NoteWorthy Newsletter and host of two annual note investing conferences, the NoteWorthy Investors Summit & National Convention. Aaron was a managing partner for a private investment company that acquired over 2,000 single-family assets nationwide and managed over $100 million in note investments.
Aaron holds a Bachelor’s degree in Science from Arizona State University. Aaron loves spending time with his children, traveling, golfing, and following sports stats.
1
What are the advantages of opening a self-directed IRA?
Some advantages of self-directed IRAs include:
Tax-deferred or tax-free profits
Investment diversity (it is possible to invest in an array of assets in your retirement account)
Potentially building wealth for future beneficiaries
2
Am I restricted to only purchasing residential property with my IRA?
You are not limited to residential real estate. Your IRA can hold various investment properties such as commercial buildings, vacant land, condominiums, mobile homes and apartment buildings, in addition to residential property.
Aaron Halderman is not an employee of Equity Trust Company. Opinions or ideas expressed are not necessarily those of Equity Trust Company nor do they reflect their views or endorsement. These materials are for informational purposes only. Equity Trust Company, and their affiliates, representatives and officers do not provide legal or tax advice. Investing involves risk, including possible loss of principal.
Equity Trust Company is a directed custodian and does not provide tax, legal or investment advice. Any information communicated by Equity Trust is for educational purposes only, and should not be construed as tax, legal or investment advice. Whenever making an investment decision, please consult with your tax attorney or financial professional.
Let’s talk about your financial future.
Schedule a one-on-one session with an expert alternative investment counselor. We’re here to answer any questions, help guide you through the process, and provide more detailed information and education specific to your journey.
We respect your privacy and will not use the information you provide for any other purpose.
Join over 100,000 subscribers who receive investing and wealth-building news and education in their inbox.
You are leaving trustetc.com to enter the ETC Brokerage Services (Member FINRA/SIPC) website (etcbrokerage.com), the registered broker-dealer affiliate of Equity Trust Company. ETC Brokerage Services provides access to brokerage and investment products which ARE NOT FDIC insured. ETC Brokerage does not provide investment advice or recommendations as to any investment. All investments are selected and made solely by self-directed account owners.
We use cookies to improve your experience on our site. By using our site, you consent to cookies.
Cookie Preferences
When you visit our website, we and our vendors use cookies and other online tracking technologies ("Cookies") to enhance user experience, analyze website performance and traffic, and provide marketing and advertising.
We use certain Cookies to enable the website to function, including for website security and to remember your settings and privacy preferences. These Cookies are always active. You can set your browser to block or alert you about these Cookies, but if you block these Cookies, some parts of the website may not function properly.
A sale of personal information can refer to disclosures of personal information to third parties who may use the information for their own purposes, such as Cookie vendors. Similarly, sharing personal information refers to disclosing personal information to third parties for cross-context behavioral advertising. In this context we sell and share personal information through our website. If you would like to opt out of sales and sharing for cross-context behavioral, please opt out of the Targeting and Analytics sections below. If you choose to use the Global Privacy Control (GPC) browser signal, you will be opted out of sales and sharing for cross-context behavioral advertising associated with the browser for which you have enabled the signal. If you use multiple browsers or devices, you will need to activate the signal for each one that you use.
You can manage your Cookies at any time by clicking the "Do Not Sell or Share My Personal Information" link in the footer of the website.
Please see our Privacy Policy for more information about our privacy practices.
These Cookies are necessary for the website to function and are always active. These Cookies are used, for example, for the security of our website and to administer your privacy preferences. You may configure your browser to block or alert you about these Cookies, but some parts of the website may not function properly if you do so.
Name
Description
Duration
Geolocation Config
This cookie is used to store the consent settings based on the visitor's location.
365 days
Cookie Preferences
This cookie is used to store the user's cookie consent preferences.
365 days
CloudFlare provides web performance and security solutions, enhancing site speed and protecting against threats.
The _cfuvid cookie is only set when a site uses this option in a Rate Limiting Rule, and is only used to allow the Cloudflare WAF to distinguish individual users who share the same IP address.
session
cf_clearance
Whether a CAPTCHA or Javascript challenge has been solved.
session
__cfseq
Sequence rules uses cookies to track the order of requests a user has made and the time between requests and makes them available via Cloudflare Rules. This allows you to write rules that match valid or invalid sequences. The specific cookies used to validate sequences are called sequence cookies.
session
cf_ob_info
The cf_ob_info cookie provides information on: The HTTP Status Code returned by the origin web server. The Ray ID of the original failed request. The data center serving the traffic
session
cf_use_ob
The cf_use_ob cookie informs Cloudflare to fetch the requested resource from the Always Online cache on the designated port. Applicable values are: 0, 80, and 443. The cf_ob_info and cf_use_ob cookies are persistent cookies that expire after 30 seconds.
session
__cfwaitingroom
The __cfwaitingroom cookie is only used to track visitors that access a waiting room enabled host and path combination for a zone. Visitors using a browser that does not accept cookies cannot visit the host and path combination while the waiting room is active.
session
cf_chl_rc_i
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
cf_chl_rc_ni
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
cf_chl_rc_m
These cookies are for internal use which allows Cloudflare to identify production issues on clients.
session
__cfruid
Used by the content network, Cloudflare, to identify trusted web traffic.
session
__cf_bm
Cloudflare's bot products identify and mitigate automated traffic to protect your site from bad bots. Cloudflare places the __cf_bm cookie on End User devices that access Customer sites that are protected by Bot Management or Bot Fight Mode. The __cf_bm cookie is necessary for the proper functioning of these bot solutions.
session
__cflb
When enabling session affinity with Cloudflare Load Balancer, Cloudflare sets a __cflb cookie with a unique value on the first response to the requesting client. Cloudflare routes future requests to the same origin, optimizing network resource usage. In the event of a failover, Cloudflare sets a new __cflb cookie to direct future requests to the failover pool.
session
Google Tag Manager loads the site's other analytics and advertising tags. It sets no cookies of its own; each tag it loads is listed under its own category and only runs with the consent that category requires.
Set on m.stripe.com to help Stripe detect fraudulent payments.
2 years
These Cookies help us understand how visitors interact with our website by collecting information about usage, traffic, and website performance. This information helps us improve the website and user experience.
Crazy Egg records how visitors scroll, click and move through pages (heatmaps and session recordings). Form fields are masked before any data leaves the browser.
Set by Cloudflare on Unbounce's content domain (js.ubembed.com) to distinguish people from automated traffic.
30 minutes
These Cookies are used by us and our advertising and marketing partners to deliver more relevant content and advertisements. They may collect information about your browser, device, and interactions across websites to help tailor advertising and measure campaign effectiveness.
Google Ads measures the results of advertising and builds audiences for showing relevant ads.
One cookie per offer (the name ends in the offer ID), recording that the visitor has already seen it.
30 days
_omappvs
Records the current visit, to decide which offers to show.
20 minutes
_omappvp
Records that the visitor has been to the site before, to decide which offers to show.
13 months
These Cookies enable enhanced features and personalisation, such as remembering your preferences and providing additional functionality. They may be set by us or our vendors. If disabled, certain website features may not operate as intended.
Calendly provides appointment scheduling for booking a consultation. The cookies below are set by Calendly's content delivery network.

 If you hold performing notes or are considering them as an investment option, it’s helpful to be prepared for potential scenarios.